Reviewed by John Brown, CSA Sep 20, 2026
Table of Contents
- What 24 Hour Home Care Actually Includes
- Personal Care, ADLs, and Daily Routines
- What It Does Not Cover
- Live-In Care vs 24 Hour Care: Staffing and Cost Differences
- Live-In Care
- 24-Hour Home Care
- The Cost of 24 Hour Home Care and What Drives It
- What Actually Moves the Hourly Rate
- Hourly Rates, Weekly Totals, and Monthly Estimates
- Paying for It: The Programs Most Families Miss
- Medicare Coverage for Home Health Care: What It Pays For
- What Medicare Will Not Pay For
- How Long Can Medicare Home Health Continue?
- When a Claim Is Denied
- What Fills the Gap
- Who Needs Round-the-Clock Care and Who Can Use Respite Instead
- Senior Care Transition Planning After a Hospital Discharge
- Information and Documents Families May Need
- How to Vet a Caregiver Agency and Avoid Family Caregiver Burnout
- Frequently Asked Questions
Last Updated: Sep 20, 2026
What 24 Hour Home Care Actually Includes
Twenty-four-hour home care generally refers to continuous, nonmedical support provided through scheduled caregiver shifts. Depending on the agency and the family’s needs, coverage may involve two or more caregivers working different shifts throughout the day and night. This Central Texas family resource explains what 24-hour home care may include, what affects its cost and how it differs from Medicare-covered home health services.
Personal Care, ADLs, and Daily Routines
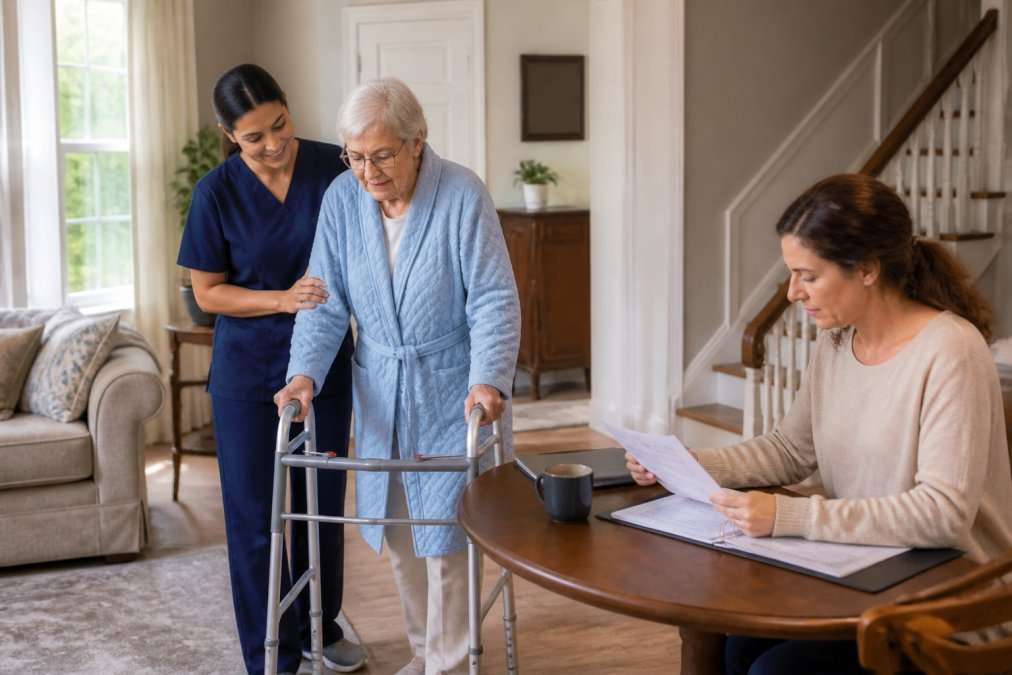
The core of round-the-clock assistance is typically hands-on help with activities of daily living, or ADLs: bathing, dressing, toileting, transferring from bed to chair, and eating. Overnight caregivers may also help with repositioning to support skin integrity and watch for nighttime confusion or wandering, though specific duties and staffing depend on the agency and the individual plan of care.
What It Does Not Cover
Nonmedical home care and Medicare-certified home health are different services. Personal-care attendants commonly help with activities such as bathing, dressing, toileting, mobility, meals, supervision and companionship. Skilled clinical services—including wound care, injections, IV therapy and monitoring an unstable medical condition—generally require an appropriately licensed healthcare professional. Permitted duties can depend on the worker’s credentials, agency policies, care plan and applicable Texas requirements. In Texas, agencies providing home health, hospice or personal-assistance services are generally licensed by the Texas Health and Human Services Commission as Home and Community Support Services Agencies, commonly called HCSSAs. Families should confirm an agency’s current license and ask which specific services it is authorized to provide. Texas HHS HCSSA information
Watch OutFamilies often assume "24 hour" means a nurse is present, but that generally isn't the case. If your parent needs clinical monitoring, home health care may need to be arranged alongside, not instead of, personal care.
Live-In Care vs 24 Hour Care: Staffing and Cost Differences
Families often hear “live-in care” and “24-hour care” used interchangeably, but they can describe very different staffing arrangements. Because agencies may define these services differently, ask exactly how coverage, sleep periods, breaks and overnight needs are handled.
Live-In Care
Live-in care generally means one caregiver stays in the home for an extended period and may have scheduled time for sleep, meals and personal breaks. It may work when a senior needs regular help and supervision but does not require someone to remain awake and available every minute of the night.
The home may need to provide the caregiver with an appropriate place to sleep and reasonable privacy. Staffing schedules, caregiver duties and overnight interruptions vary by agency.
24-Hour Home Care
Twenty-four-hour care generally uses multiple caregivers working rotating shifts so someone is available throughout the day and night. This may be considered when a senior has frequent nighttime needs, wandering, repeated falls, significant mobility limitations or cannot safely be left without assistance.
Twenty-four-hour nonmedical home care does not automatically mean that a nurse is present. If skilled nursing or clinical monitoring is needed, those services may need to be arranged separately through an appropriately licensed provider.
| Feature | Live-In Care | 24 Hour Care |
|---|---|---|
| Caregiver sleep | Sleep periods typically scheduled | Awake coverage typically maintained |
| Staffing model | One primary caregiver | Two or more rotating shifts |
| Best for | Stable, low-acuity needs | Dementia, fall risk, overnight needs |
| Continuity | Same person most days | Depends on agency scheduling |
| Privacy | Caregiver lives on site | Caregiver leaves between shifts |
Pro TipAsk the agency how they handle shift changes and call-offs. Continuity of care is where 24 hour arrangements quietly fail, and it's the question most families forget to ask.
The Cost of 24 Hour Home Care and What Drives It
There is no single national rate. Understand the structure of the bill and the variables that move it, so you can pressure-test a quote instead of accepting it.
What Actually Moves the Hourly Rate
What can influence the rate:
- Overnight and weekend shifts, which may carry a premium over weekday daytime rates
- Dementia care or behavioral support requiring trained staff
- Higher acuity, such as two-person transfers or a Hoyer lift
- Rural or hard-to-staff service areas, where agencies may account for travel time and mileage
- Holiday coverage, which some agencies bill at a higher rate
What can bring it down:
- A live-in arrangement where the caregiver sleeps on site and the agency is not paying for awake overnight hours
- Splitting coverage with family caregivers during daytime hours, so you only buy the shifts you cannot staff yourself
- Private hire, though that shifts screening, payroll taxes, workers' compensation, and liability onto you
Hourly Rates, Weekly Totals, and Monthly Estimates
Agencies typically provide an hourly rate, which is then used to calculate weekly totals based on shift hours, and subsequently monthly estimates. Rates vary widely by market and care level, so you need a written quote based on an in-home assessment.
A few structural realities are worth internalizing:
- The hourly rate for 24 hour care can sometimes be lower than the rate for a short visit, as agencies may offer different pricing structures for longer commitments.
- Shift minimums matter. Some agencies may have minimum billing hours per shift.
- The rate you are quoted is usually the agency's rate, which covers supervision, insurance, payroll taxes, training, and scheduling, in addition to the caregiver's wage.
Pro TipAsk for the quote in weekly terms, not monthly. Weekly totals are easier to verify against the shift schedule, and they make it obvious when an agency has quietly padded the hours.
Paying for It: The Programs Most Families Miss
Cost is only one aspect. Understanding payment options is crucial, as many families may not be aware of all available resources.
- Long-term care insurance. If your parent bought a policy years ago, it may cover custodial care, the bathing, dressing, and supervision that Medicare will not touch. Policies vary enormously, so read the elimination period and the daily benefit cap before assuming coverage.
- Veterans' benefits. Veterans and surviving spouses may qualify for a VA pension benefit commonly known as Aid and Attendance, which can help pay for in-home personal care. It is generally needs-based and typically requires supporting documentation from a physician; the application process can take time, so it's worth starting early and confirming current requirements directly with the U.S. Department of Veterans Affairs (VA.gov).
- Medicaid home and community-based waivers. In Texas, programs administered through the Texas Health and Human Services Commission, such as STAR+PLUS, can help cover personal care at home for those who qualify. Eligibility rules and interest-list wait times change over time, so check current details directly with Texas HHS.
- Life insurance conversion. Some policies allow you to convert a death benefit into a living benefit to pay for long-term care. It is not widely advertised, but it exists.
- Reverse mortgage or home equity. For a parent who owns their home and wants to age in it, this is sometimes the only asset large enough to fund years of care.
Medicare Coverage for Home Health Care: What It Pays For
Medicare coverage for home health care, administered by the Centers for Medicare & Medicaid Services (CMS), is often narrower than families expect. Understanding the rules before you need them can be crucial for navigating covered claims.
Medicare may cover certain part-time or intermittent home health services when a person needs qualifying skilled care, is considered homebound and receives services from a Medicare-certified home health agency. Before services begin, a doctor or another qualified healthcare provider, such as a nurse practitioner, must evaluate the person, confirm the need and order the care. Medicare does not pay for 24-hour care at home or personal care when that is the only service needed. Families should verify current eligibility and coverage directly with Medicare or their Medicare Advantage plan. Medicare home health coverage
What Medicare Will Not Pay For
Medicare does not pay for custodial care: bathing, dressing, meals, toileting, transferring, and supervision, the type of support nonmedical home care typically provides. Nor does it pay for 24-hour coverage in the home; the Medicare home health benefit is built around intermittent skilled visits, not continuous custodial shifts.
How Long Can Medicare Home Health Continue?
Medicare home health is not automatically limited to one short episode. Coverage may continue when the person continues to meet Medicare’s eligibility requirements and the treating provider and home health agency document the ongoing need for qualifying services. Care plans and certifications are reviewed periodically. Because individual circumstances and Medicare Advantage rules can differ, families should confirm continuing coverage with the agency and health plan.
When a Claim Is Denied
Denials happen, and some are overturned on appeal. If Medicare denies a home health claim:
- Request the detailed denial notice in writing.
- Ask the agency whether they can help you file an appeal; some agencies assist with this process.
- File a redetermination request within the deadline stated on the notice. Missing the deadline forfeits the appeal.
- Keep your own copy of the plan of care, the physician's orders, and the visit notes.
What Fills the Gap
In Texas, Medicaid may cover some personal care needs through home and community-based waiver programs administered by Texas Health and Human Services, though eligibility and waitlists vary. Long-term care insurance, veterans' benefits, and private pay are other common sources families consider. The Medicare home health coverage guidelines lay out the homebound and skilled-need requirements in detail, and the Eldercare Locator can connect Central Texas families to their regional Area Agency on Aging for waiver and eligibility information.
Who Needs Round-the-Clock Care and Who Can Use Respite Instead
Round-the-clock care is a nonmedical, custodial service, different from the Medicare-certified skilled home health described above. It's often worth considering when nighttime risk is real: dementia-related wandering, frequent falls, or a parent who cannot safely transfer alone, or when the primary family caregiver's own health and well-being are being affected.
Ask yourself three questions:
- Does your parent get up at night unassisted?
- Has there been a fall in the last six months?
- Is the current caregiver sleeping, eating, and working normally?
Senior Care Transition Planning After a Hospital Discharge
Senior care transition planning should begin before discharge, not the day your parent comes home. Before discharge, ask the hospital or rehabilitation case manager which services have been ordered, when they are expected to begin and who is responsible for each next step. Medicare-certified home health, nonmedical home care, medical equipment, transportation and follow-up appointments may involve different organizations and payment sources.
Information and Documents Families May Need
- Current medication list
- Written discharge instructions
- Follow-up appointments
- Home health or therapy orders
- Medical-equipment instructions
- Emergency contact information
- HIPAA authorization, when appropriate
- Texas Medical Power of Attorney or other advance-planning documents already in place
- These documents are not all required for discharge. Families needing legal guidance about decision-making authority, capacity or guardianship should consult a qualified Texas elder-law attorney. Guardianship is a court process, and less restrictive alternatives may sometimes be available.
How to Vet a Caregiver Agency and Avoid Family Caregiver Burnout
Questions worth asking every agency:
- Who supervises the caregiver, and how often?
- What happens when a caregiver calls out sick?
- Can I meet the caregiver before the first shift?
- How do you handle a complaint?
Key TakeawayThe strongest care plans name a backup for every role. If your family's plan depends entirely on one person, it isn't a plan.
Senior Industry Services offers a Central Texas directory, educational resources and the Senior-AI assistant to help families explore senior-care topics and locate relevant resource categories. Directory inclusion is not an endorsement or guarantee of any provider. Families should contact providers directly, verify credentials and services, and make their own informed decisions. Senior-AI provides general educational information and does not diagnose needs, determine an appropriate service or replace advice from healthcare, legal or financial professionals.
Frequently Asked Questions
How much does 24 hour home care cost?
The pricing for 24 hour home care depends on your location, the level of personal care assistance needed, and whether you hire a caregiver agency or an independent aide. Live-in arrangements and hourly shift care may have different pricing structures, and specialized care like dementia support or mobility assistance can influence rates. Because these variables can significantly impact the total, ask each agency for a written weekly and monthly estimate before signing anything.
Does Medicare pay for 24 hour home care?
Medicare coverage for home health care is limited and does not pay for round-the-clock custodial care, such as help with bathing, dressing, or companionship. It may cover short-term skilled nursing, therapy, or a home health aide when a doctor certifies a skilled need and you meet homebound requirements. Medicare does not cover 24 hour home care itself. Confirm current rules with Medicare or a discharge planner.
What is the difference between live-in care and 24 hour care?
Live-in care places one caregiver in the home who sleeps overnight and works defined shifts. True 24 hour care uses two or more caregivers covering waking hours around the clock, so someone is always alert. The right choice depends on fall risk, dementia symptoms, and whether overnight supervision is medically necessary.
How does 24 hour home care work for seniors with dementia?
Dementia care often requires awake overnight staff because wandering, confusion, and nighttime agitation create safety risks. A caregiver agency typically assigns aides with dementia training and builds a care plan around routines, fall prevention, and medication reminders. Continuity of care matters most: ask how the agency keeps the same caregivers on a consistent schedule.
When a family is facing an urgent discharge or trying to arrange support at home, the number of decisions can feel overwhelming. Senior Industry Services helps Central Texas families begin with clear educational information, explore local resource categories and prepare better questions for providers. Visit Senior-AI or browse the SIS directory to explore possible next steps.
Educational notice: This article provides general information and is not medical, legal, financial or insurance advice. Services, eligibility requirements, licensing information and benefit rules can change. Confirm current information directly with the appropriate agency, health plan, provider or qualified professional.
Sources: